Indian equities surge as oil prices retreat
Nifty 50 rose 8.58% to 25,030.35 and the Sensex gained 8.82% in the week to 6 November 2026. Brent settled at $98.32 a barrel. The rally reflects relief in imported energy and financial conditions, but its durability still depends on the real economy and company earnings.
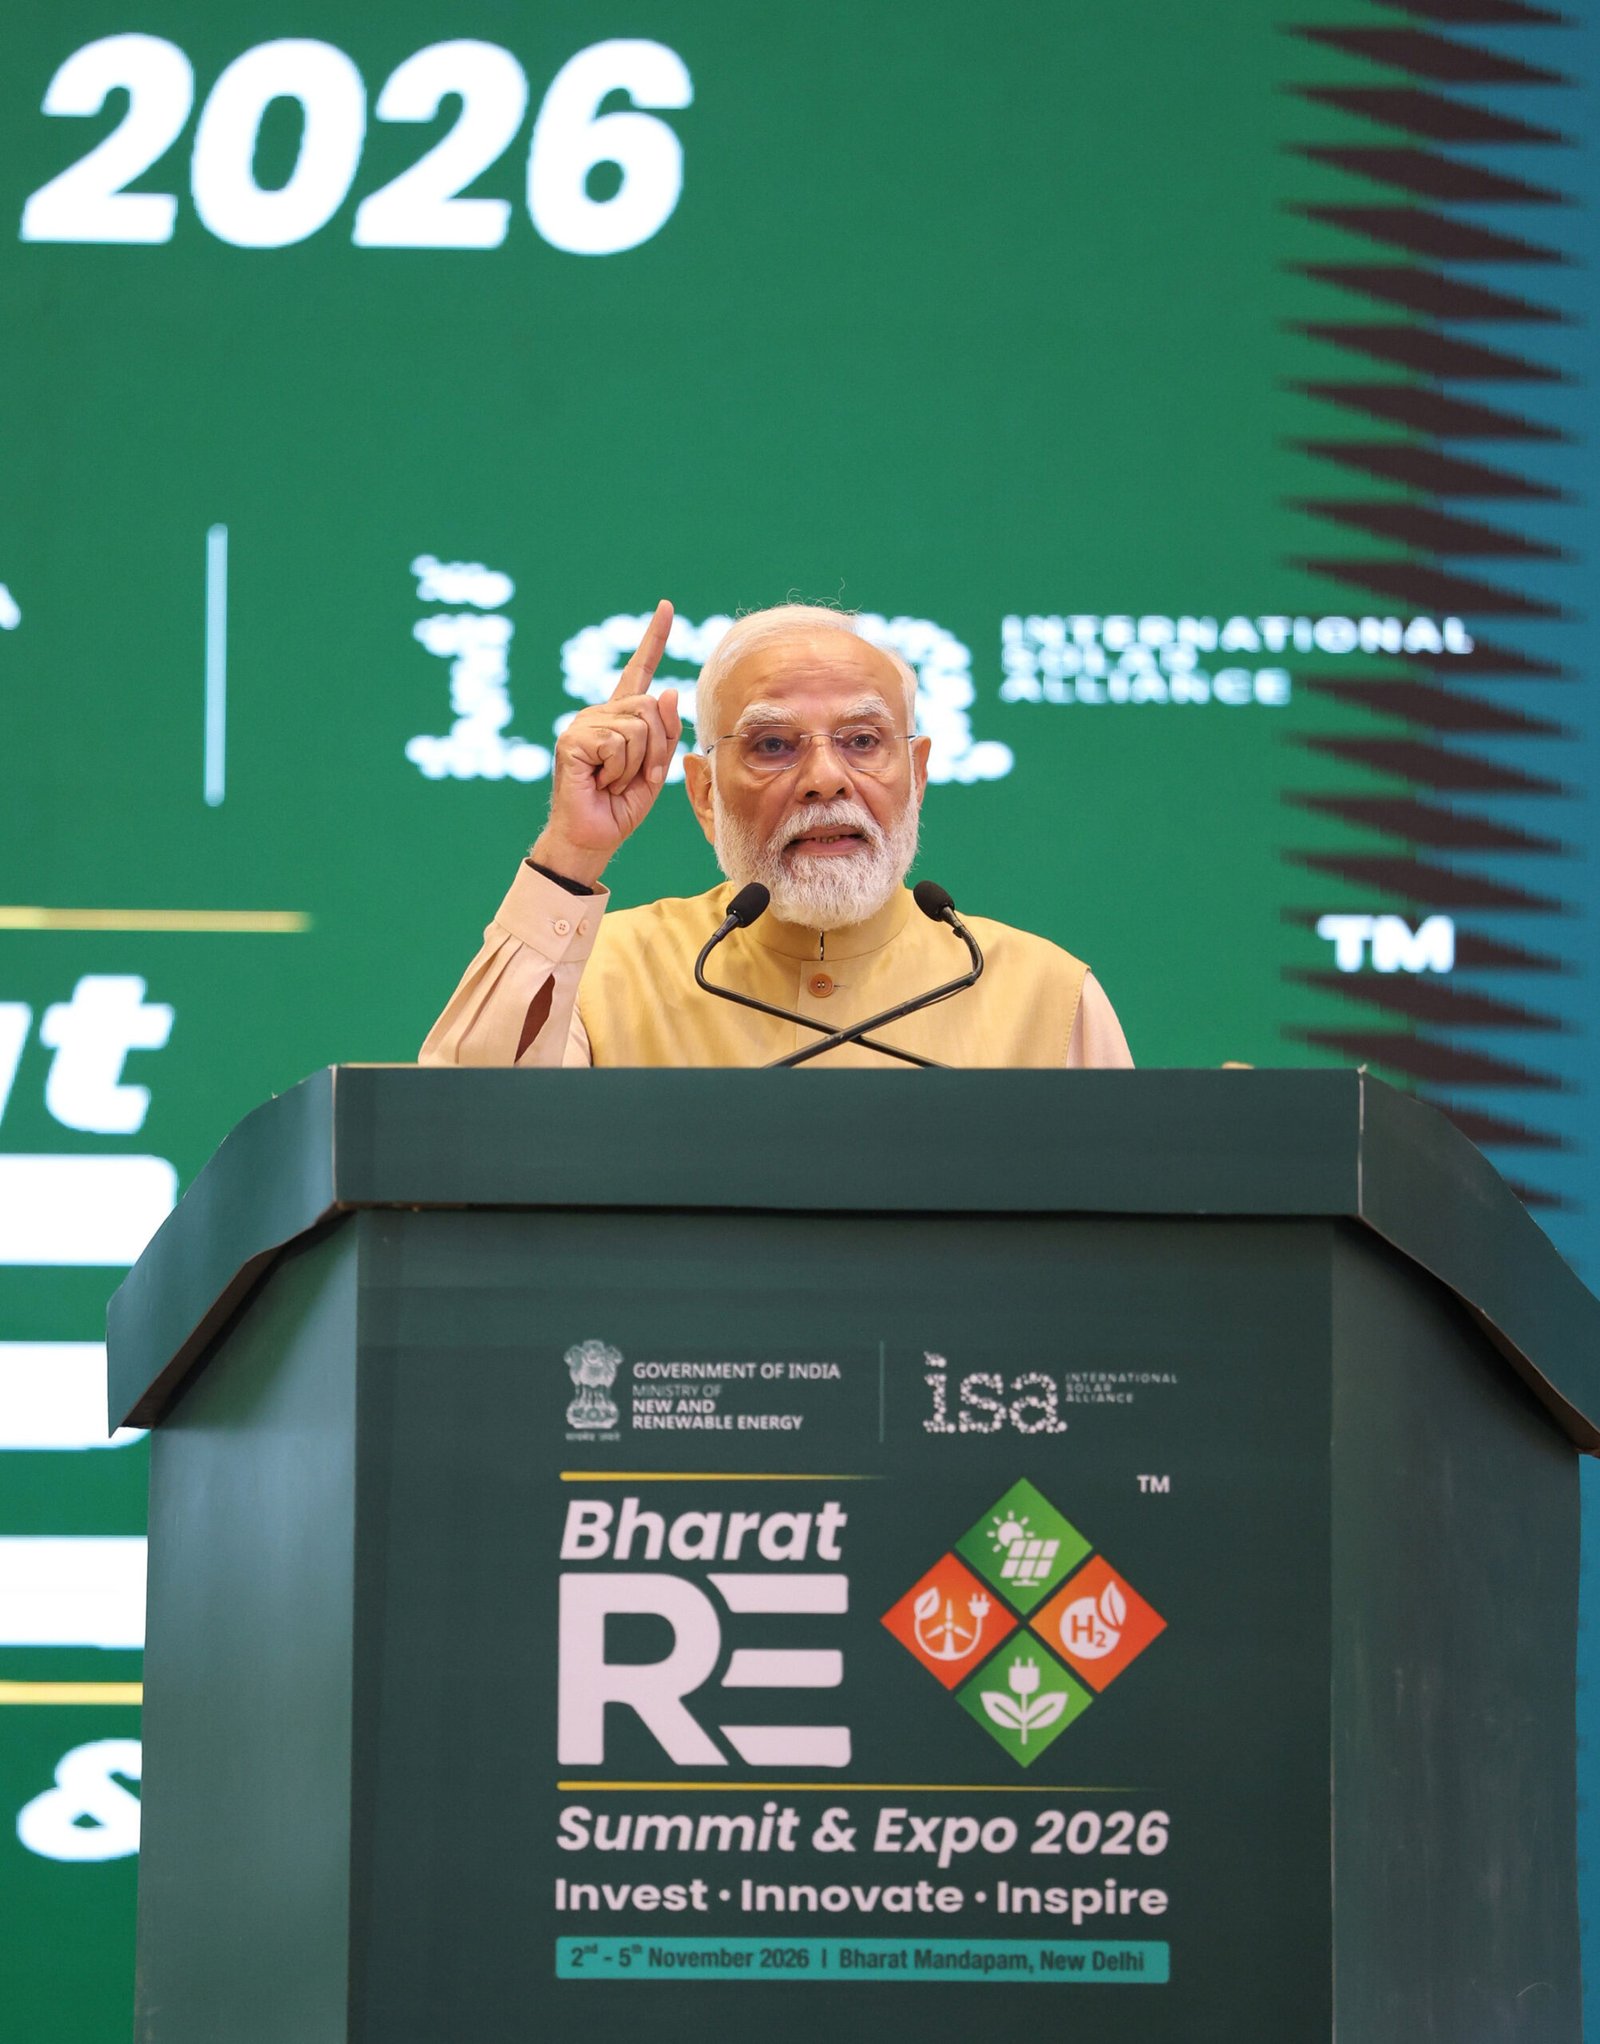
Download the complete 12-page illustrated research edition, with the approved A4 layout, source register, real-event photography and Watch & Listen section. Research cut-off: 8 November 2026, 10:00 IST.
Download Newsletter (PDF)Executive Intelligence Brief
Indian benchmark equities gained sharply in the week ended 6 November. Nifty 50 rose 8.58% to 25,030.35, while Sensex climbed 8.82% to 81,028.02. Price recovery is not proof that corporate cash earnings grew by the same proportion. [S1][S2]
Brent settled at $98.32 on 6 November versus $117.64 on 30 October. The decline may moderate imported costs, but effects on realised oil imports depend on freight, insurance, inventories and exchange rates. [S3]
Manufacturing
October PMI 54.7, down from September [S5]
Services
October PMI 55.8, up from September [S6]
Monetary policy
RBI repo 5.50% [S12]
External buffer
FX reserves $717.056bn to 30 Oct [S4]
Headline Analysis: Oil Relief and Equity Rebound
The rapid reduction in oil’s risk premium changed the valuation narrative for an energy-importing economy. Lower Brent futures can provide relief through the trade bill, inflation and financing, but actual delivered petroleum prices may react with a lag. [S3]
The rupee was reported around ₹93.91 per US dollar on Friday and the 10-year sovereign yield near 7.19%. These traded prices do not constitute a new RBI rate decision. [S2]
OIL PRICE
Brent $98.32 per barrel
IMPORT COST
Physical cargo and insurance terms
RUPEE / CPI
Price transmission with a lag
CREDIT / EARNINGS
Confirm financing and cash flow
Markets & Macro Dashboard
The observations below refer to different periods. A market close, a weekly reserve stock and a monthly PMI cannot be described as one simultaneous snapshot.
| Indicator | Reading | Observation | Interpretation |
|---|---|---|---|
| Nifty 50 | 25,030.35 | 6 Nov | +8.58% week | Benchmark recovery [S1] |
| Sensex | 81,028.02 | 6 Nov | +8.82% week | Broad repricing [S2] |
| Brent crude | $98.32/bbl | 6 Nov settle | Oil premium retreats [S3] |
| USD / INR | ~93.91 | 6 Nov close | Currency firmed [S2] |
| India 10Y | ~7.19% | 6 Nov close | Term yield eased [S2] |
| FX reserves | $717.056bn | 30 Oct stock | External buffer [S4] |
| Manufacturing PMI | 54.7 | October | Expansion moderated [S5] |
| Services PMI | 55.8 | October | Expansion improved [S6] |
| IIP | +6.7% YoY | September | Production reading [S10] |
| Gross GST | +22.9% YoY | October | Nominal revenue [S11] |
EQUITIES
Recovery is substantial; earnings breadth remains important.
ENERGY / FX
Lower import pressure is conditional on delivered costs.
PMI MIX
Manufacturing and services moved differently.
RESERVES
Weekly stock is not an intervention estimate.
Global Economy & Geopolitics
Although oil prices fell, regional supply and shipping risk did not disappear. Insured cargo availability, chartering and refinery feedstock costs govern the pass-through to India’s import bill. [S3]
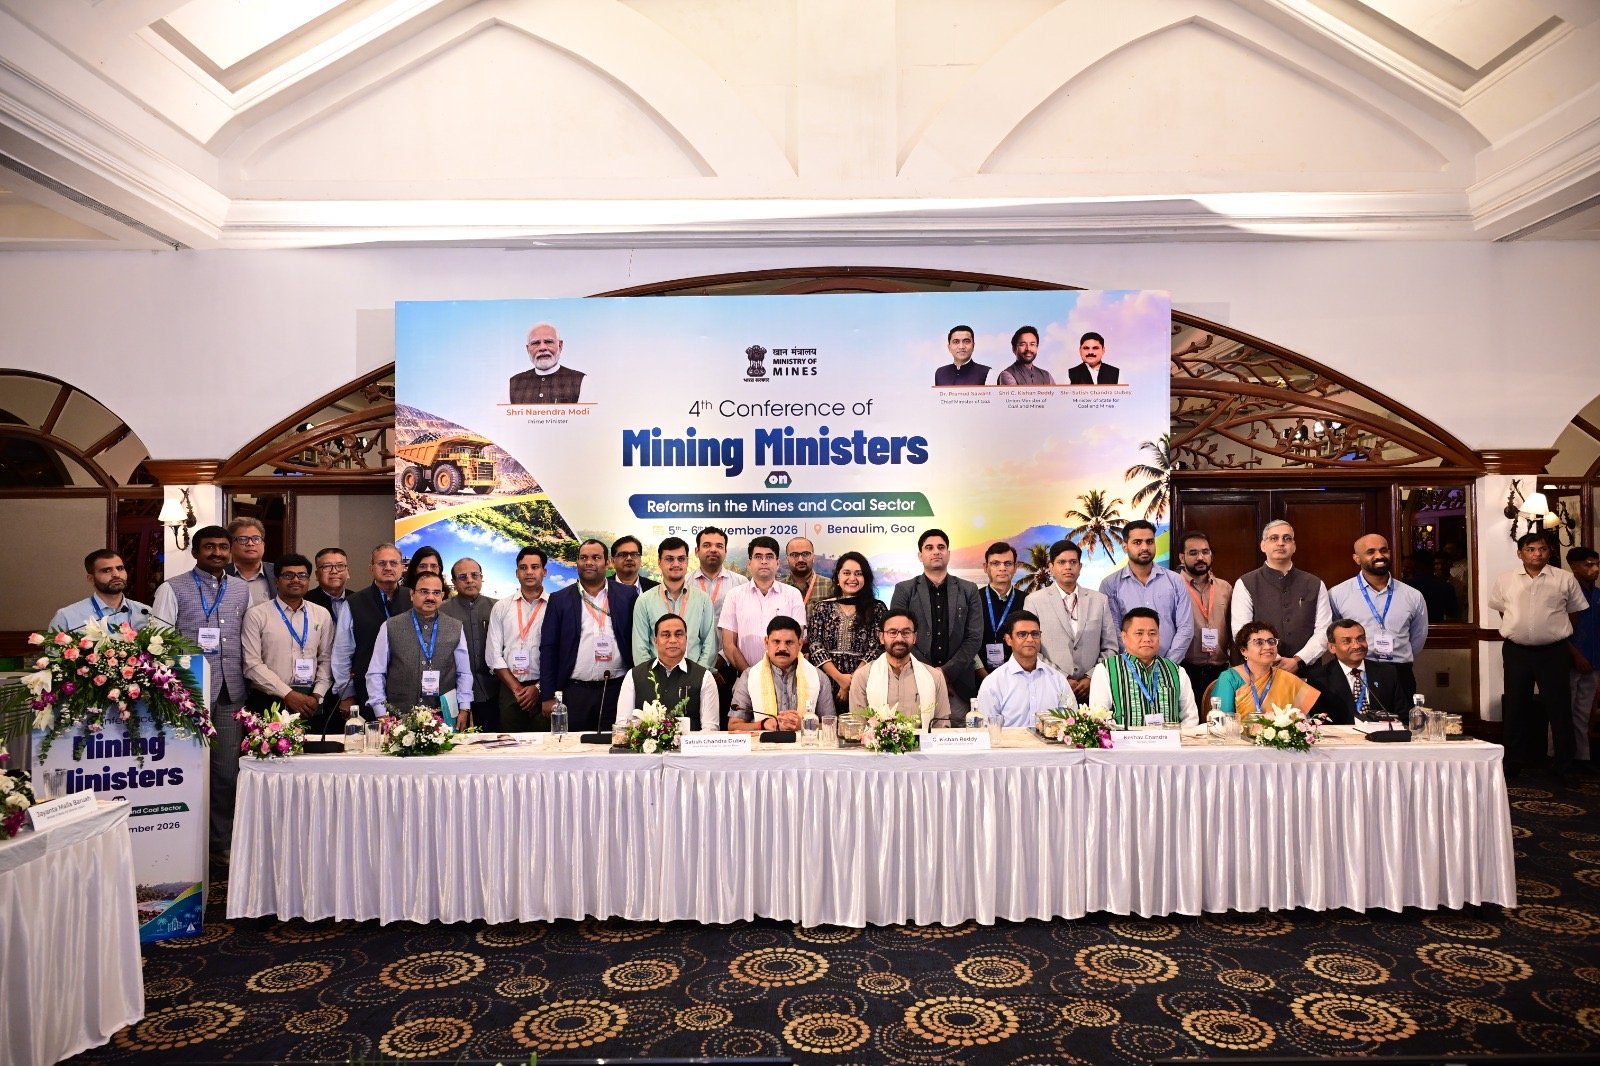
The Fourth Conference of Mining Ministers addressed state coordination and the critical minerals ecosystem. The announced ninth auction tranche comprised 20 mineral blocks, with an additional exploration-licence tranche covering 11 blocks. Announcements must be distinguished from financed production. [S13]
ENERGY SECURITY
Physical deliveries remain decisive.
INDIA INVESTMENT
Project financing and implementation require monitoring.
GLOBAL FUNDING
Currency and yields influence the cost of capital.
MINERALS
Exploration is not yet industrial output.
India Macro & Liquidity Radar
RBI’s policy repo remained at 5.50% following the October decision. Traded yields, cash liquidity and bank financing terms may change separately. The latest referenced reserve stock stood at $717.056bn for the week to 30 October. [S4][S12]
The RBI’s November credit release reported 15.4% year-on-year growth for the covered NBFC credit series through September. This must not be misidentified as the growth rate for all scheduled commercial bank lending. [S8]
POLICY
Repo and traded yields are different indicators.
CREDIT
Segment-specific lender data require precise labels.
RESERVES
Transaction and valuation effects both matter.
CPI
Monitor the next inflation release.
| Window | Data | Use |
|---|---|---|
| 8 Nov afternoon | Muhurat session | After the research cutoff [S9] |
| 10 Nov | Exchange holiday | Settlement planning [S9] |
| Next CPI | October inflation | Price pass-through |
| Weekly RBI | Reserves and liquidity | External conditions |
Research & Data Brief
The week brought rapid financial-market repricing, not uniform improvement in all real-economy measures. Manufacturing PMI moderated to 54.7, services PMI improved to 55.8 and the published reserve stock declined. [S4][S5][S6]
NIFTY
+8.58%
BRENT
$98.32
RUPEE
~93.91/USD
MFG PMI
54.7
SERVICES PMI
55.8
RESERVES
$717.056bn
Company Research Lab: Reliance Industries
Reliance Industries’ September-quarter results offer a listed-company lens on the energy and investment cycle. Refining, petrochemicals, retail and digital activity respond differently to crude prices and financing. [S7]
GROSS REVENUE
₹3,62,268 crore | Q2 FY27
CONSOLIDATED EBITDA
₹62,409 crore | Q2 FY27
REPORTED PAT
₹29,550 crore including JVs and associates
CAPITAL EXPENDITURE
₹38,153 crore | Q2 FY27
Lower crude can reduce some costs while also changing inventory valuations and upstream economics. Company valuation depends on segment margins, capex, financing and cash generation; EBITDA is not the same as profit after tax.
Global-to-India Transmission
The imported-energy channel moves from landed crude and marine insurance through currency, inflation, credit terms and eventually corporate margins. The speed and magnitude differ by sector and contract.
RELIEF | EQUITIES
Nifty +8.58% weekly
RELIEF | OIL
Brent $98.32
WATCH | CURRENCY
Rupee ~93.91/USD
WATCH | CPI
October data ahead
WATCH | RESERVES
$717.056bn to 30 Oct
SUPPORT | SERVICES
October PMI 55.8
POSITIVE | GST
October gross +22.9%
WATCH | EARNINGS
Cash conversion and guidance
Scenario Matrix
These monitoring weights are editorial attention allocations, not statistically estimated event probabilities, forecast returns or portfolio recommendations.
BASELINE | 45%
Oil relief persists while physical cargoes continue. Consumer demand holds up; margins recover selectively.
ADVERSE | 35%
Supply risks return, raising insured import costs, currency pressure and equity risk premia.
RELIEF | 20%
Cheaper delivered energy, calmer FX and stronger cash conversion broaden the improvement.
Independent tests: physical oil and freight, currency and reserve composition, credit spreads, and realised operating cash flows.
Continuity & Revisions
Issue 008 described robust tax and industrial indicators against high oil and financing costs. At 30 October, the Nifty stood at 23,053.10 and Brent at $117.64. [S14]
By 6 November, Nifty had recovered to 25,030.35 and Brent had fallen to $98.32. The major change was the external cost and market discount-rate narrative, rather than new GDP or company-wide earnings evidence. [S1][S2][S3]
EQUITIES
Nifty +8.58% weekly
ENERGY
Brent $98.32
ACTIVITY
Manufacturing 54.7, services 55.8
EXTERNAL
Reserves $717.056bn
Week Ahead & ALBORITHM Bottom Line
| Period | Check | Why |
|---|---|---|
| 8 Nov afternoon | Muhurat session | After 10:00 IST cutoff |
| 10 Nov | NSE holiday | Trading and settlement |
| Next release | October CPI | Energy price impact |
| Quarterly filings | Company earnings | Cash margins |
| Weekly | RBI reserve data | External buffers |
Indian markets enter the new week with a material easing in oil and equity-market pressure. Whether this becomes a durable economic improvement will depend on delivered prices, currency stability, inflation and real cash earnings.
Sources, Credits & Watch / Listen
[S2] Business Standard market review
[S3] Reuters Brent settlement
[S4] RBI FX reserves
[S5] HSBC manufacturing PMI
[S6] HSBC services PMI
[S7] Reliance reporting
[S8] RBI NBFC credit release
[S9] NSE exchange calendar
[S10] MoSPI industrial output
[S11] GST Council
[S12] RBI repo policy
[S13] PIB minerals auction 5 Nov
[S14] ALBORITHM previous Issue 008
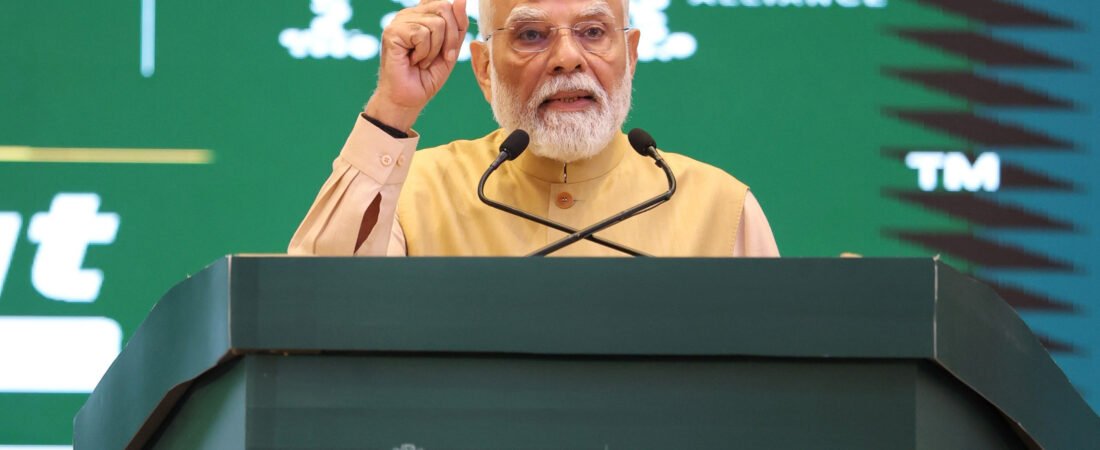
[S15] PIB Modi address image 219363
[S16] PIB Mining Ministers photo 6 Nov
Photo credit: PIB / Government of India, 2 and 6 Nov 2026.
Explore the weekly explainer and podcasts, with clearly labelled destinations.
Discover more research and stories from ALBORITHM.
Subscribe to alborithm
Get new documentaries, articles and podcasts directly in your inbox.