HEADLINE INTELLIGENCE
EIGHT WEEKS DOWN AS INDIA FACES THE RBI TEST WITH GROWTH STILL FIRM
India enters the 7 October policy decision with an uncomfortable split. Factories are improving while financial conditions tighten. Nifty fell 3.11% in the shortened week, the rupee closed at 96.3150 per dollar, August industrial output grew 8.0% and September manufacturing PMI rose to 55.1. The RBI must weigh resilient activity against persistent price and currency pressure.
01 | Executive Intelligence Brief
The growth engine remains firm, but markets are pricing a harder financial environment. Q1 FY27 real GDP grew 7.8%. August industrial production rose 8.0% year on year. September manufacturing PMI improved to 55.1 from 52.8. Yet Nifty and Sensex extended their weekly losing streak to eight weeks. The rupee ended 1 October at 96.3150 per dollar, Brent settled at $102.25 a barrel on 2 October, India 10-year yields were indicated near 7.21%, and foreign exchange reserves stood at $747.557 billion for the week ended 25 September.
Continue the series through the ALBORITHM newsletter archive. Compare the framework with Issue 003.
02 | Headline Analysis | Growth Meets the Policy Test
The latest factory numbers make the policy decision harder to reduce to a single story. Real activity has strengthened, yet the price of capital remains high and the currency is under pressure. A business can sell more units and still earn less on each sale if energy, imported components and funding become more expensive.
For households, the channels arrive at different speeds. Imported costs may first compress a producer’s margin, then appear in selling prices or smaller discounts. Higher borrowing costs can affect new loans before existing fixed-rate contracts. The outcome depends on pricing power, debt structure and the persistence of the shock.
Decision rule: Improving order books need to become sustained sales and cash generation. At the same time, lower delivered energy costs and more orderly currency conditions would make the growth buffer more valuable. An equity rebound alone cannot establish either condition.
03 | Markets & Macro Dashboard
| Indicator | Latest observation | Context |
|---|---|---|
| Nifty 50 | 22,421.95 | -3.11% week | Eighth weekly loss | 1 Oct close |
| BSE Sensex | 71,909.70 | -2.69% week | Holiday-shortened week |
| USD / INR | 96.3150 | Onshore close | 1 Oct |
| India 10Y | About 7.21% | OTC indication | 1 Oct |
| Brent crude | $102.25/bbl | 2 Oct settlement |
| FX reserves | $747.557bn | Week ended 25 Sep |
| Industrial output | +8.0% YoY | August quick estimate |
| Manufacturing PMI | 55.1 | September final |
India was closed on Friday, 2 October, while global energy markets traded. Observation dates therefore remain attached to each series. A mixed-date dashboard is useful only when the dates are explicit.
04 | Global Economy & Geopolitics
Energy relief must reach the physical supply chain. Brent settled Friday at $102.25 a barrel. The G7 agreed on oil and diesel stock releases. At the 17:00 IST cutoff, Reuters reporting on an OPEC+ agreement in principle to leave November targets unchanged had not yet become a final communique in the evidence set used for this issue.
Iraq’s tanker company reported a two-million-barrel transit through Hormuz. Separately, the Houthis claimed an attack on an Aramco facility in Riyadh, without immediate Saudi confirmation in the cited reporting. A successful transit and an unverified damage claim should not be merged into one supply conclusion.
Stock releases can bridge shortages, but lasting relief requires sustained supply and shipping access.
India’s import burden depends on benchmark prices, freight, insurance and the rupee.
Higher required returns can compress valuations before current earnings weaken.
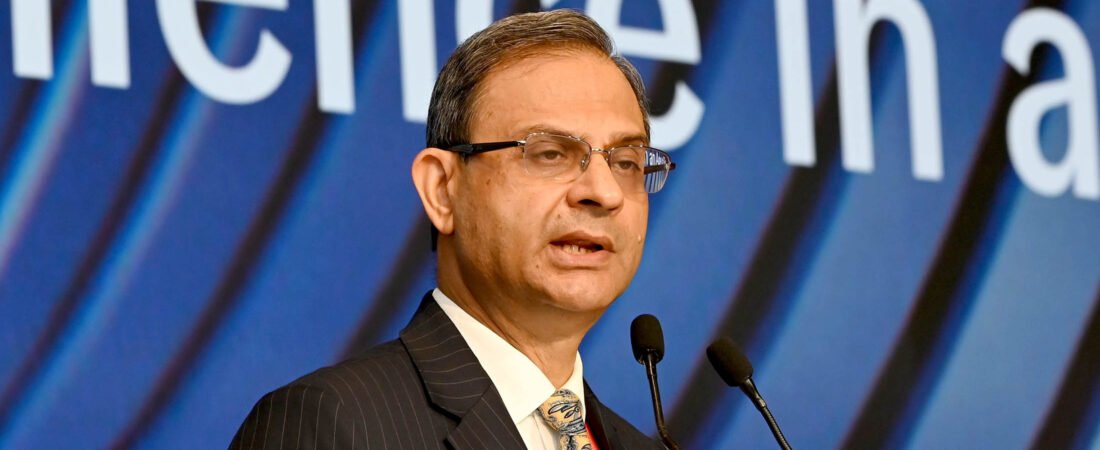
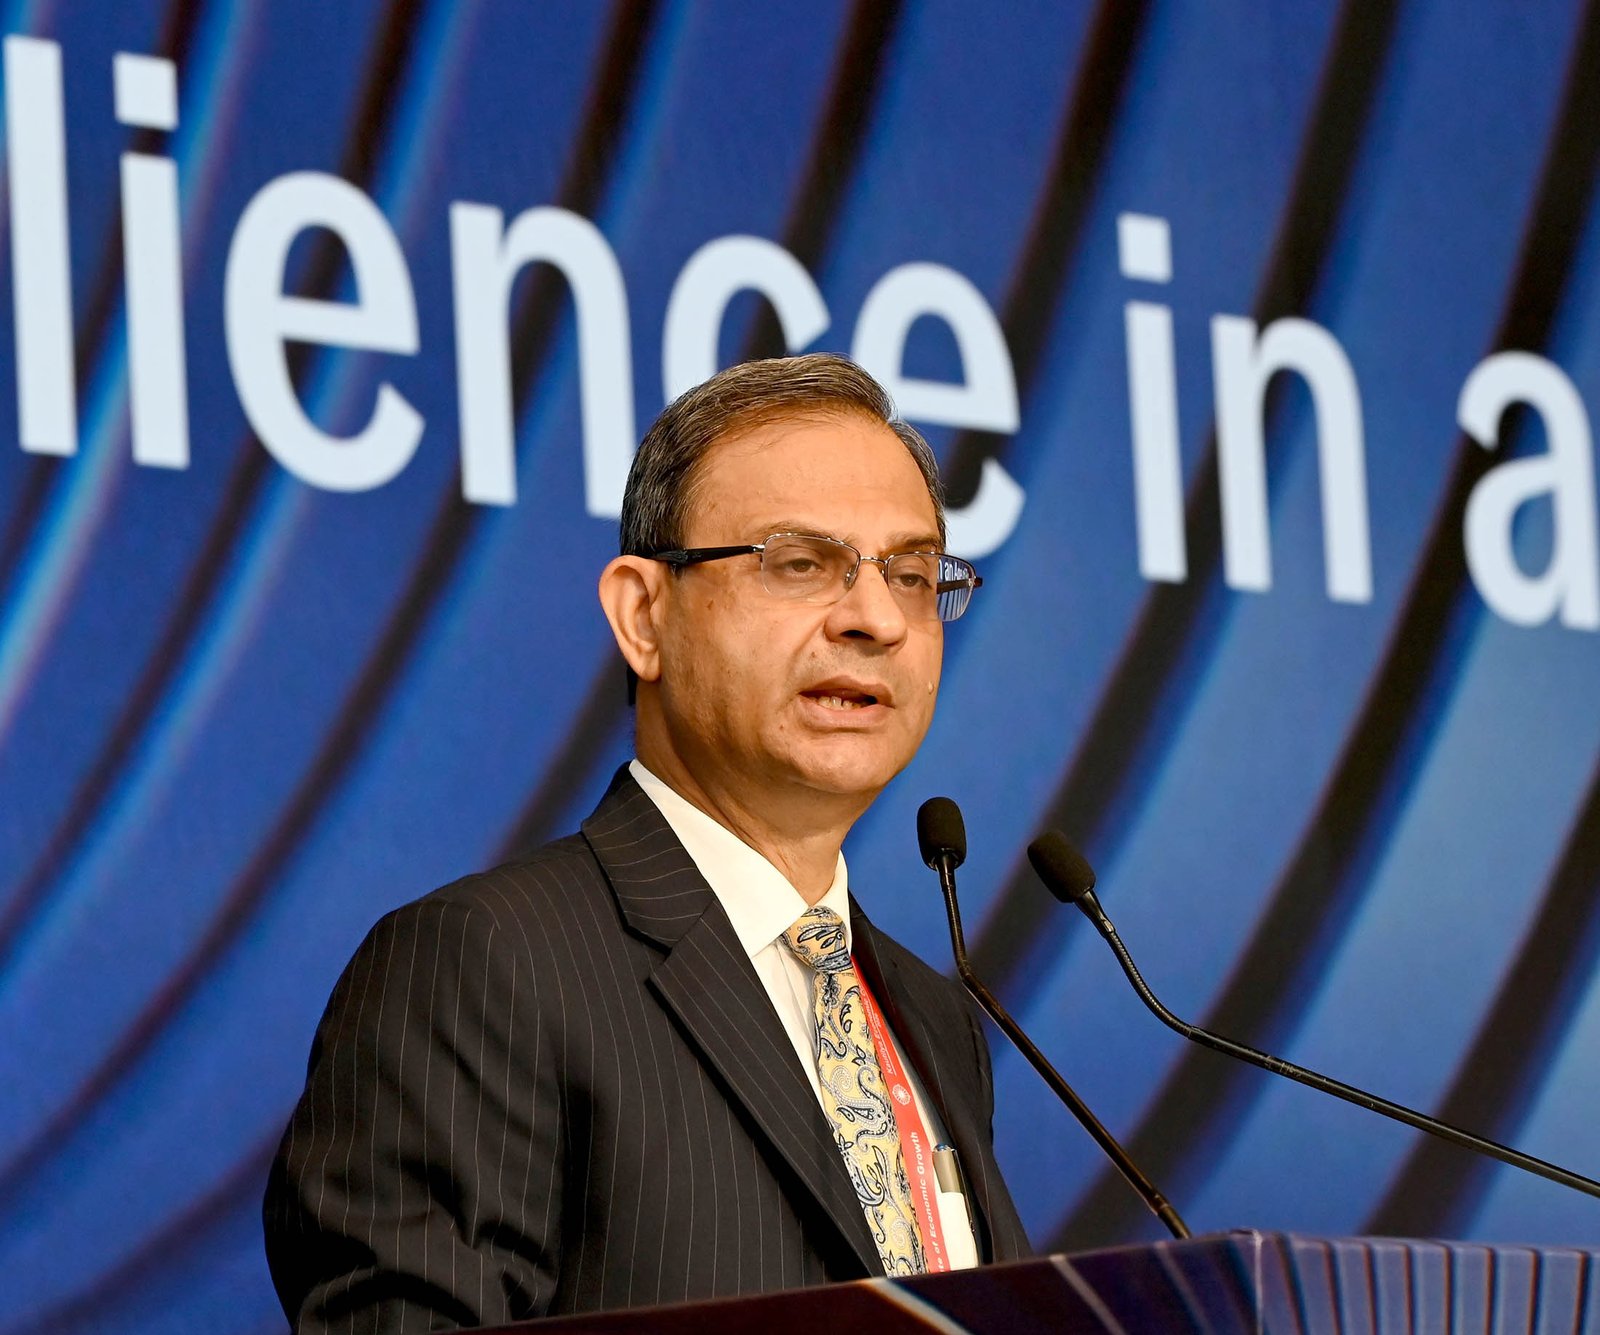
RBI Governor remarks on resilience and supervision should not be treated as an advance MPC decision.
05 | India Macro & Liquidity Radar
The RBI policy meeting runs from 5 to 7 October, with the decision due on 7 October. The reported repo-rate baseline is 5.25%. Discussion of a 25 basis point increase remains an expectation, not an announced change.
August CPI inflation was 4.82%, with food inflation at 5.95% on the provisional official reading. Stronger activity gives policymakers a different starting point from an economy already contracting, but it does not remove uncertainty about the eventual cost of tighter financial conditions.
GLOBAL YIELDS | RBI LIQUIDITY | INDIA 10Y | CREDIT / FX | PRICES / GROWTH
06 | Rules, Policy & Release Calendar
| Regime / release | Status | Next watch |
|---|---|---|
| RBI policy | 5.25% repo baseline | decision 7 Oct | Resolution, voting and guidance |
| FX reserves | $747.557bn | week ended 25 Sep | Valuation effects and composition |
| H2 borrowing | Rs 7.86 lakh crore planned | Auction demand and maturity absorption |
| Fiscal accounts | Apr-Aug deficit: 41.9% of annual target | Revenue and expenditure timing |
| Inflation | August CPI 4.82% | September CPI due 12 Oct |
07 | Research & Data Brief
Better activity is evidence, but its composition still matters. IIP measures production, PMI describes the balance of survey responses, and GST measures nominal collections affected by imports, prices, refunds and timing. None is a substitute for real household consumption.
August manufacturing grew 9.0%, while mining contracted 5.6%.
Consumer durables grew 11.1%; non-durables rose 2.1%.
Domestic GST grew 10.1%; import-linked revenue rose 25.9%.
A dollar reserve decline combines transactions and valuation changes. It is not a direct estimate of intervention.
08 | Company Research Lab | Tata Consultancy Services
TCS offers a timely test of how currency, overseas demand and AI spending interact. On 1 October, TCS and Best Buy announced an agreement to transition Best Buy’s India Global Capability Center to TCS under a multi-year arrangement. The release describes a planned evolution into an AI-focused capability centre.
The TCS board is scheduled to consider Q2 FY27 financial results and a second interim dividend on 8 October. No Q2 outcome or dividend amount was known at this issue’s cutoff. The announcement is an upcoming evidence point, not an earnings conclusion.
The analytical question is whether new work produces profitable, cash-generating growth. A weaker rupee can support translated revenue, but onsite costs, hedges, wage changes and the currency mix affect the net result. Deal announcements do not establish a quarterly revenue or profit contribution.
09 | Global-to-India Transmission
The same global shock does not affect every Indian business equally. An importer may face a higher rupee cost before it can change selling prices. An exporter may gain from translation while facing weaker client budgets. A lender may reprice assets and liabilities at different speeds.
The market therefore needs company-level evidence alongside the macro dashboard. Import intensity, hedging, contract duration, debt maturity and pricing power determine the eventual earnings effect. Broad index weakness cannot establish a uniform profit decline.
10 | Signals, Risks & Monitoring Radar
| RED | EQUITIES | Eight consecutive weekly declines. Watch whether selling pressure broadens into earnings revisions. |
| RED | ENERGY COST | Brent remains above $100 at Friday settlement. Delivered costs can differ materially. |
| AMBER | RUPEE | 96.3150/USD at Thursday close. Track the speed and orderliness of adjustment. |
| AMBER | INDIA 10Y | About 7.21% on the dated OTC series. The policy statement can change the curve. |
| GREEN | OUTPUT | August IIP +8.0%. Check sector breadth and subsequent revisions. |
| GREEN | TAX RECEIPTS | Gross GST +14.7%. Read import and refund components separately. |
11 | Scenario Matrix
Activity remains firm, oil stays costly without a sustained fresh surge, and currency adjustment remains orderly. The RBI contains expectations while company margins face uneven pressure.
Energy or funding costs rise further, firms face weaker pricing power and households become more cautious. Earnings pressure spreads beyond the most import-sensitive businesses.
Delivered energy costs ease, currency volatility recedes and policy communication reduces uncertainty. Better activity data then have more scope to support earnings expectations.
Scenario weights are editorial monitoring allocations, not statistical probabilities or investment advice.
12 | Continuity, Revisions & Week Ahead
Issue 003 separated domestic resilience from pressure in oil, currencies and bonds. This week strengthened that distinction. The equity losing streak lengthened and the rupee weakened, while industrial production and the final manufacturing survey improved. The market warning persisted; the evidence for an immediate collapse in activity did not.
| Date | Event | Why it matters |
|---|---|---|
| 5-7 Oct | RBI MPC | Rate, inflation outlook and liquidity guidance |
| 8 Oct | TCS results meeting | Client demand, margins and execution |
| Daily | Oil, freight, INR and bond yields | Whether external costs and financing ease together |
| 12 Oct | September CPI scheduled | Next retail inflation release, beyond this issue’s cutoff |
India reaches RBI week with firmer factories and weaker financial markets. Growth provides room to absorb shocks, but it does not cancel the cost of oil, currency pressure or expensive capital.
The next useful evidence is the policy resolution followed by company earnings and cash flow. Read them together before changing the thesis.
- MoSPI / PIB | August IIP quick estimates | 28 Sep 2026.
- HSBC / S&P Global manufacturing PMI, reported by DD India | 1 Oct 2026.
- Informist | September GST collections | 1 Oct 2026.
- Financial Express | equity closing levels and weekly changes | 1 Oct 2026.
- Reuters / MarketScreener | rupee close | 1 Oct 2026.
- Reuters | Brent and WTI settlements | 2 Oct 2026.
- RBI data via PTI / DT Next | reserves for week ended 25 Sep.
- Trading Economics | India 10-year OTC indication | 1 Oct 2026.
- MoSPI / PIB | August CPI provisional release | 14 Sep 2026.
- PIB | Q1 FY27 GDP backgrounder | 1 Sep 2026.
- Ministry of Finance / PIB | H2 borrowing plan | 25 Sep 2026.
- Business Standard | RBI meeting dates and repo-rate baseline | 2 Oct 2026.
- PTI / Business Standard | RBI Governor at Kautilya Economic Conclave | 3 Oct 2026.
- TCS | Best Buy India GCC agreement | 1 Oct 2026.
- TCS exchange filing | board meeting scheduled for 8 Oct 2026.
- CGA data reported by The Tribune | April-August fiscal accounts | 30 Sep 2026.
- Reuters | Iraqi crude transit through Hormuz | 3 Oct 2026.
- Reuters | OPEC+ agreement in principle | 4 Oct 2026.
- PIB photographs 217660 and 217659 | New Delhi | 3 Oct 2026.
- Reuters | Houthi claim and unconfirmed damage status | 3 Oct 2026.
- Reuters | G7 oil and diesel reserve-release agreement | 2 Oct 2026.
- Issue control | Issue 004 | ISO Week 40 | research cut-off 04 Oct 2026, 17:00 IST.
Explore the weekly explainer and podcasts, with clearly labelled destinations.
Discover more research and stories from ALBORITHM.
Subscribe to alborithm
Get new documentaries, articles and podcasts directly in your inbox.