Investment pledges face India’s inflation test
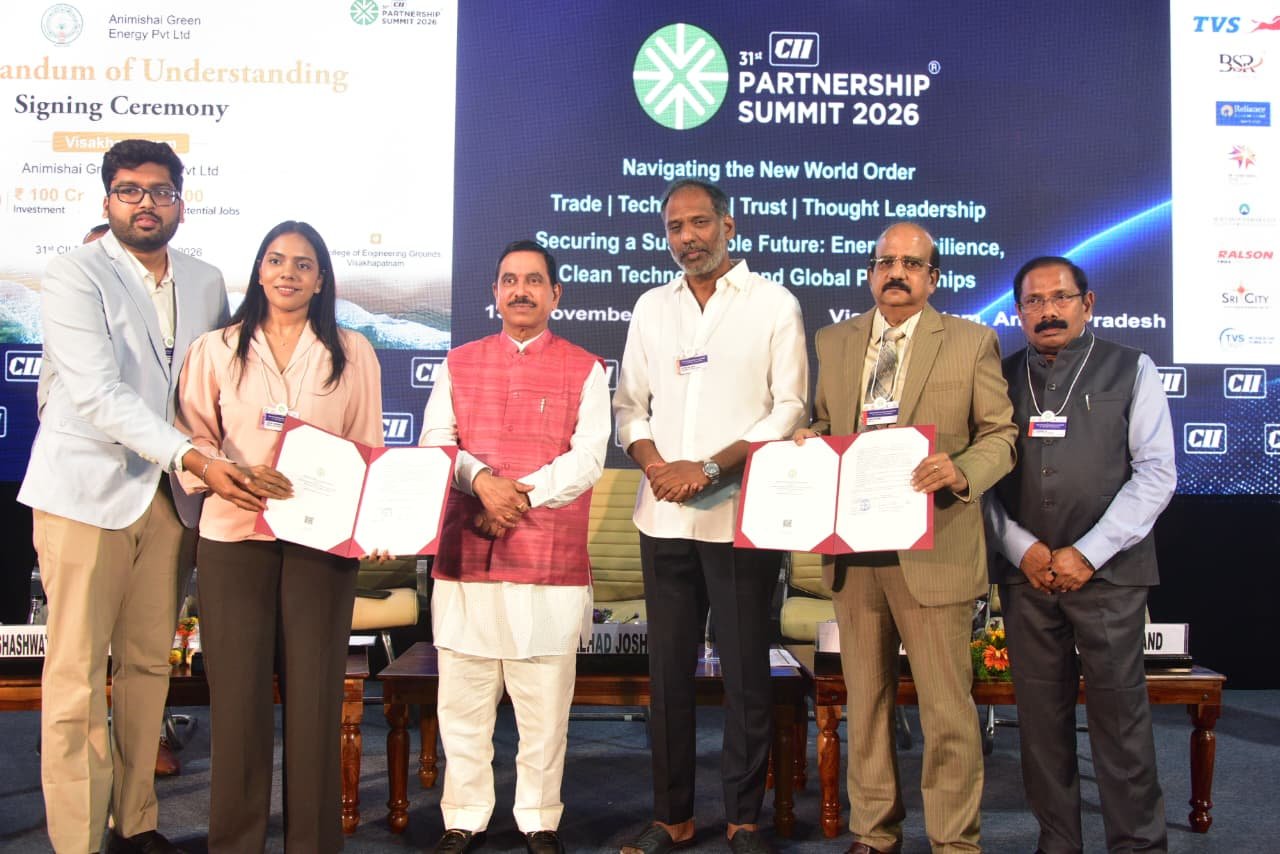
India inflation October 2026 reached 6.09% while the Visakhapatnam CII Partnership Summit put major industrial and energy investment proposals in focus. Memoranda of understanding are investment intentions, not yet deployed capital.
THE WEEK IN SIX SIGNALS
Prices
CPI 6.09%.
Food
Food CPI 8.94%.
Equities
Nifty 25,144.30.
Trade
Total exports +16.66%.
RBI
Repo 5.50%.
Reserves
$719.55bn to 6 Nov.
Complete illustrated 12-page A4 edition, including source register, documentary photography and Watch & Listen. Research cut-off: 15 November 2026, 13:00 IST.
Download Newsletter (PDF)Executive Intelligence Brief
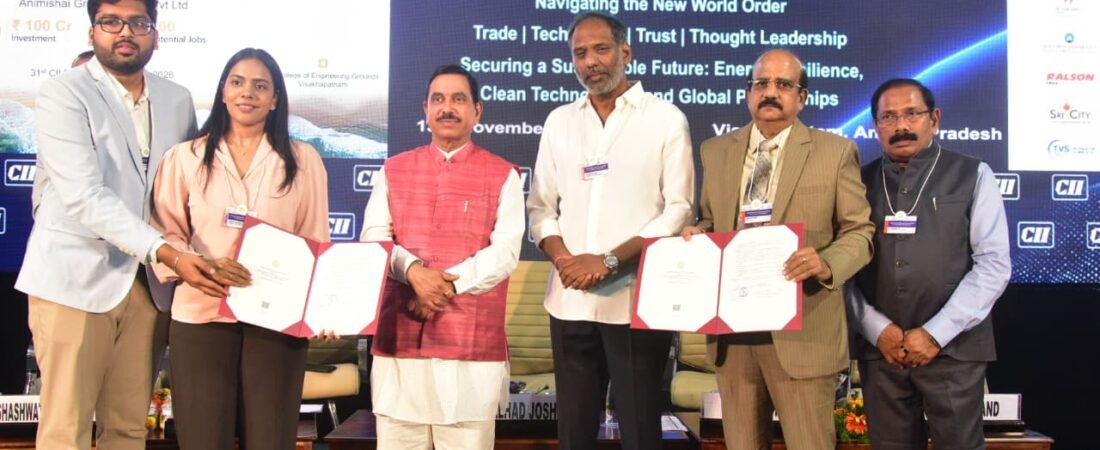
At the 31st CII Partnership Summit in Visakhapatnam, Andhra Pradesh presented new industrial and energy investment agreements. These are announced intentions, not yet funded capital expenditure or productive capacity. Meanwhile, India’s October 2026 headline consumer price inflation reached 6.09% and food inflation 8.94%, intensifying the cost and execution test. [S1][S7]
Inflation
Headline CPI 6.09%; food CPI 8.94%.
External trade
April–October exports estimated at $568.84bn.
Market close
Nifty 25,144.30; Sensex 81,592.45 on 13 Nov.
Policy rate
RBI repo remained at 5.50%.
Reserve buffer
RBI reserves $719.547bn on 6 Nov.
Investment
Finance, permits and construction determine conversion.
Headline Analysis: Investment Pledges and Inflation
India’s investment pipeline faces a more difficult price backdrop. The Visakhapatnam summit brought together political leaders, companies and international delegations around proposed manufacturing, technology, infrastructure and energy projects. Memoranda of understanding alone do not establish the timing or scale of actual capital formation. [S7][S11]
October’s CPI increase to 6.09% was accompanied by food inflation of 8.94%. Costly credit, power, imported components and land can all affect proposed projects differently, while higher food prices reduce household real spending power. [S1]
Prices
Food inflation and real consumption
Policy
Rate expectations and RBI communication
Funding
Bank credit and capital costs
Execution
Orders, land, power and construction
Investment can ultimately lift exports, productivity and employment. These benefits require confirmation through project-level reporting rather than ceremony totals.
Markets & Macro Dashboard
Monthly price releases, market closes and weekly reserve statistics have different reference dates. The dashboard preserves those distinctions.
| Indicator | Reading | Observation | Context |
|---|---|---|---|
| CPI | 6.09% | Oct, year on year | Provisional, above 6%. [S1] |
| Food CPI | 8.94% | Oct, year on year | Higher household price pressure. [S1] |
| Merchandise exports | $309.06bn | Apr–Oct, +21.96% | Goods only. [S2] |
| Total exports | $568.84bn | Apr–Oct, +16.66% | Goods and services. [S2] |
| Nifty 50 | 25,144.30 | 13 Nov close | Session -0.61%. [S4] |
| Sensex | 81,592.45 | 13 Nov close | Session -0.39%. [S4] |
| Repo | 5.50% | 13 Nov policy stock | Not a market lending rate. [S5] |
| FX reserves | $719.55bn | 6 Nov stock | RBI weekly figure. [S3] |
Competing signals
Inflation
Headline breaches tolerance ceiling.
Trade
Exports advanced in April to October.
Equities
One weak session is not the full growth story.
External buffers
Reserve stock remains substantial.
Global Economy & Geopolitics
Global interest rates, energy prices and exchange-rate movements affect India’s imported inflation and corporate hurdle rates. The domestic CPI rise coincided with stronger cumulative exports, leaving the central question of price and financing transmission. [S1][S2][S6]
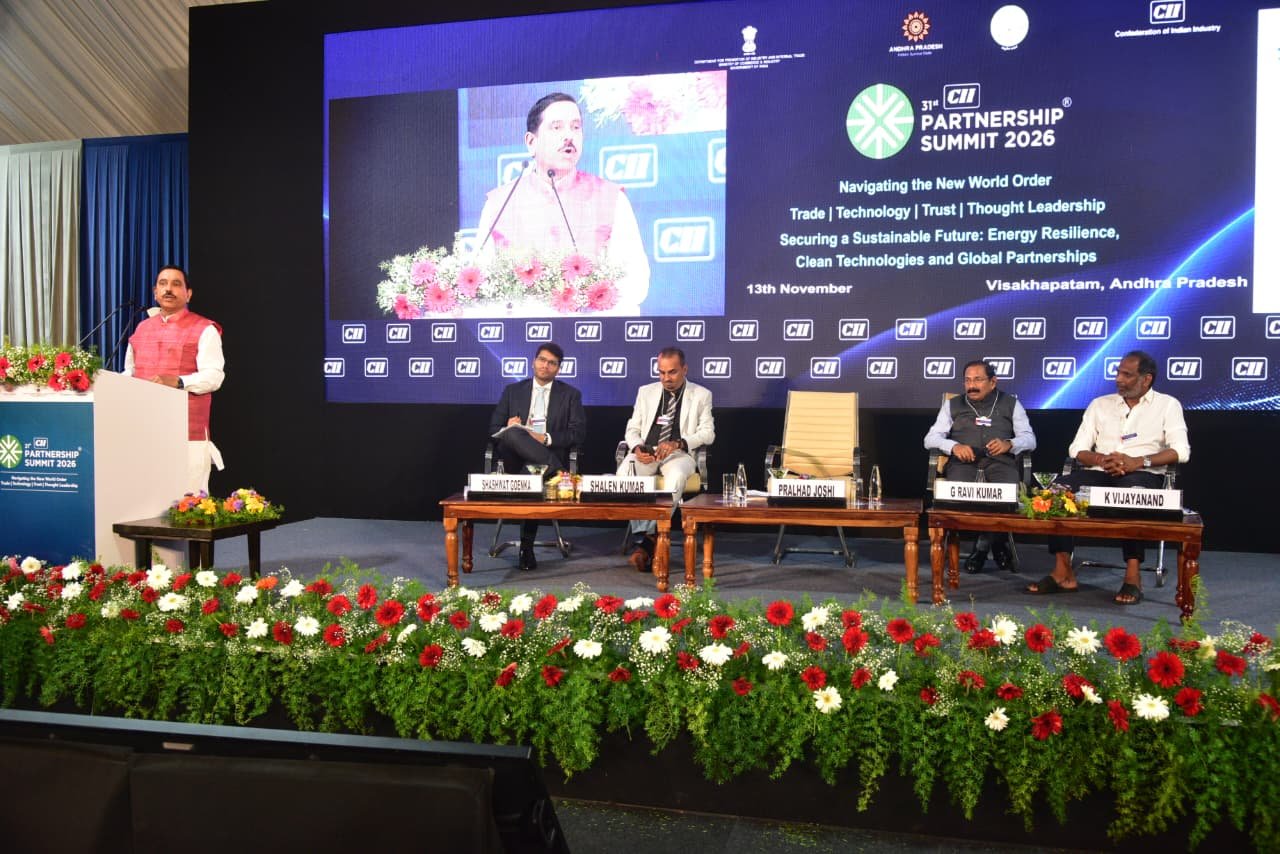
Energy transition pledges face an execution test
Projects discussed at the summit require financing, permits, grid integration and credible demand before announced capacity becomes operational. [S11][S12]
Global rates
Funding choices depend on international and Indian yields.
India capacity
Grid access and project funding precede output.
Risk
Higher prices can compress real demand and margins.
Signposts
Orders, project cash flow and commissioning.
India Macro & Liquidity Radar
October headline CPI of 6.09% and food inflation of 8.94% make the path of retail prices central to policy expectations. The 5.50% repo rate is a policy benchmark, not a promise that all borrowing costs will remain unchanged. [S1][S5]
RBI reported reserve holdings of $719.547bn for 6 November, a weekly rise of $2.490bn. Movements reflect transactions and valuation, not solely currency-market intervention. [S3]
Food costs
Real household purchasing power
Rupee
Imported cost translation
Credit
Funding rates and bank liquidity
Margins
Pricing power and free cash flow
Rules, Policy & Release Calendar
| Release / monitor | Observation | Exposure | Next validation |
|---|---|---|---|
| Headline CPI | Oct 6.09% | Household prices | Next MoSPI release [S1] |
| Food CPI | Oct 8.94% | Consumption | Component data |
| Repo | 5.50% | Funding | RBI policy and operations [S5] |
| FX reserves | $719.55bn to 6 Nov | External buffer | Next weekly RBI release [S3] |
| Exports | +16.66% Apr–Oct | External demand | Next trade print [S2] |
Research & Data Brief
Investment memoranda document intentions; CPI, trade and reserve publications report measured statistics. The distinction matters when comparing public commitments with the actual level of production or cash investment.
Inflation
October CPI 6.09% and food 8.94%.
Trade
Apr–Oct total exports $568.84bn.
Policy
Repo rate 5.50%.
Previous prices
September CPI 5.54%.
External buffer
Reserves $719.55bn on 6 Nov.
Market prices
Nifty 25,144.30 on 13 Nov.
Company Research Lab: Tata Motors Passenger Vehicles
In a 13 November exchange filing, Tata Motors Passenger Vehicles reported Q2 FY27 consolidated revenue of ₹96,900 crore, up 34% year on year. Its profitability and free cash flow did not move uniformly with the revenue figure, providing a current-quarter case study in margin transmission. [S8]
Q2 revenue
₹96,900 crore | +34% YoY
Q2 EBITDA
₹6,000 crore
JLR revenue
£5.9bn | +20.3%
Domestic Tata PV
₹20,400 crore | +51%
Jaguar Land Rover reported a 6.6% EBITDA margin and the domestic passenger vehicle operation 4.0%. Group free cash flow was negative. Product mix, raw-material costs and working capital are therefore essential to the analysis. [S8]
Global-to-India Transmission
Oil, currency and global rates affect import costs, financing and company valuations. October’s CPI increase must be examined alongside domestic food supply and the actual rupee cost of imports. [S1][S2][S6]
Energy
Physical oil and fuel costs
Imports
Delivered and insured costs
INR
Exchange-rate translation
Credit
Market and lending rates
Earnings
Cash margin conversion
The links in this chain are measurable. Neither a futures price change nor a single policy headline establishes the full cause of retail inflation.
Signals, Risks & Monitoring Radar
Risk: food
Food CPI rose to 8.94%.
Risk: funding
Repo 5.50%; company funding costs differ.
Watch: INR
RBI reference 94.1997, 13 Nov.
Watch: CPI
October headline 6.09%.
Watch: reserves
$719.55bn, stock to 6 Nov.
Positive: exports
Total exports +16.66%.
Positive: goods
Merchandise exports +21.96%.
Watch: profits
Margins and free cash flow after costs.
Scenario Matrix: Prices, Funding and Growth
These are illustrative monitoring weights, not calibrated event probabilities or forecasts of securities returns.
Baseline | 45%
Food inflation moderates slowly. Trade and credit remain stable while RBI waits for confirmation.
Adverse | 35%
Food and energy prices stay elevated, squeezing consumption and corporate margins. Investment is delayed.
Relief | 20%
Improved food supply and lower landed energy costs support real demand and funded projects.
Independent validation tests
Food prices
Components, supply and persistence
Currency
INR and imported input costs
Rates
Government yields and credit spreads
Earnings
Cash generation and management guidance
Continuity, Revisions & Forward Intelligence
The transition from Issue 009 to Issue 010 includes new October CPI data and investment commitments made at the CII summit. Those commitments are relevant, but remain distinct from executed capital investment.
Prices
Headline CPI 6.09%.
Food
Food inflation 8.94%.
Markets
Nifty -0.61%; Sensex -0.39% on Friday.
Exports
Apr–Oct total +16.66%.
Week ahead
| Cadence | Evidence | Why it matters |
|---|---|---|
| From 16 Nov | RBI operations and bonds | Funding expectations |
| This week | Corporate earnings and input prices | Margins and consumption |
| Weekly | RBI reserve data | Liquidity and valuation |
| Global | Oil and central-bank signals | Imported price pressure |
Sources, Credits & Watch / Listen
[S2] Commerce Ministry exports
[S3] RBI reserves, 6 Nov
[S4] DIPAM market data 13 Nov
[S5] RBI monetary policy
[S6] Reuters markets and oil
[S7] PIB CII summit 12 Nov
[S8] Tata Motors PV Q2 filing
[S9] RBI currency
[S10] NSE closing data
[S11] PIB summit energy session
[S12] PIB event photograph
[S13] ALBORITHM previous Issue 009
[S14] MoSPI price components
[S15] Commerce trade notes
[S16] RBI weekly supplement
Images: lead illustration reproduced from ALBORITHM’s approved Issue 010 podcast artwork; secondary event photograph credited to PIB Vijayawada, 13 November 2026. All statistics retain their observation dates.
Explore the weekly explainer and podcasts, with clearly labelled destinations.
Discover more research and stories from ALBORITHM.
Subscribe to alborithm
Get new documentaries, articles and podcasts directly in your inbox.