BRICS CLOSES AS INDIA’S $100-OILTEST DEEPENS
BRICS closes in New Delhi with a wider trade, payments and technology agenda just as Gulf disruption keeps Brent above $100, weakens the rupee and extends Indian equities’ losing streak. Strong growth and record foreign-exchange reserves are meaningful buffers; the issue is how fast external energy stress migrates into inflation, rates, earnings and fiscal trade-offs.
01 | Executive Intelligence Brief
02 | Headline Analysis – BRICS meets the energy shock
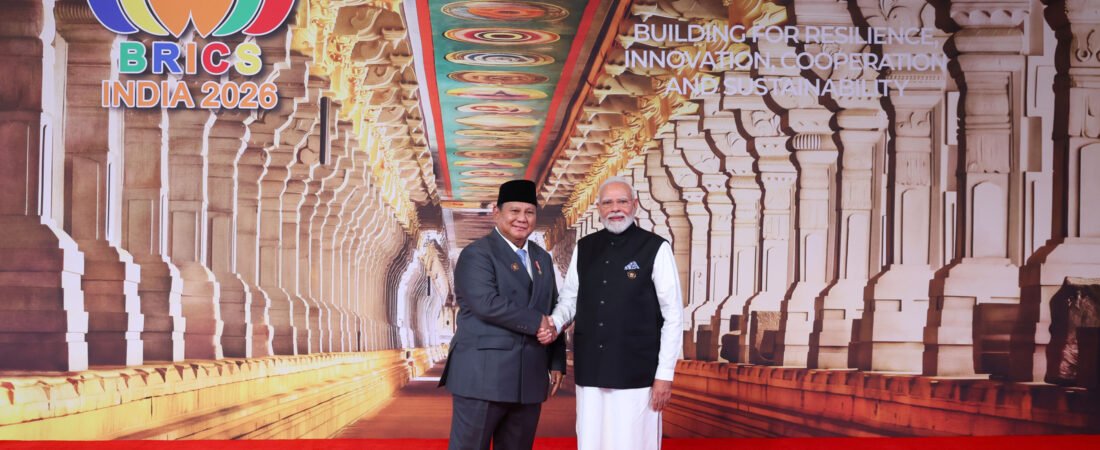
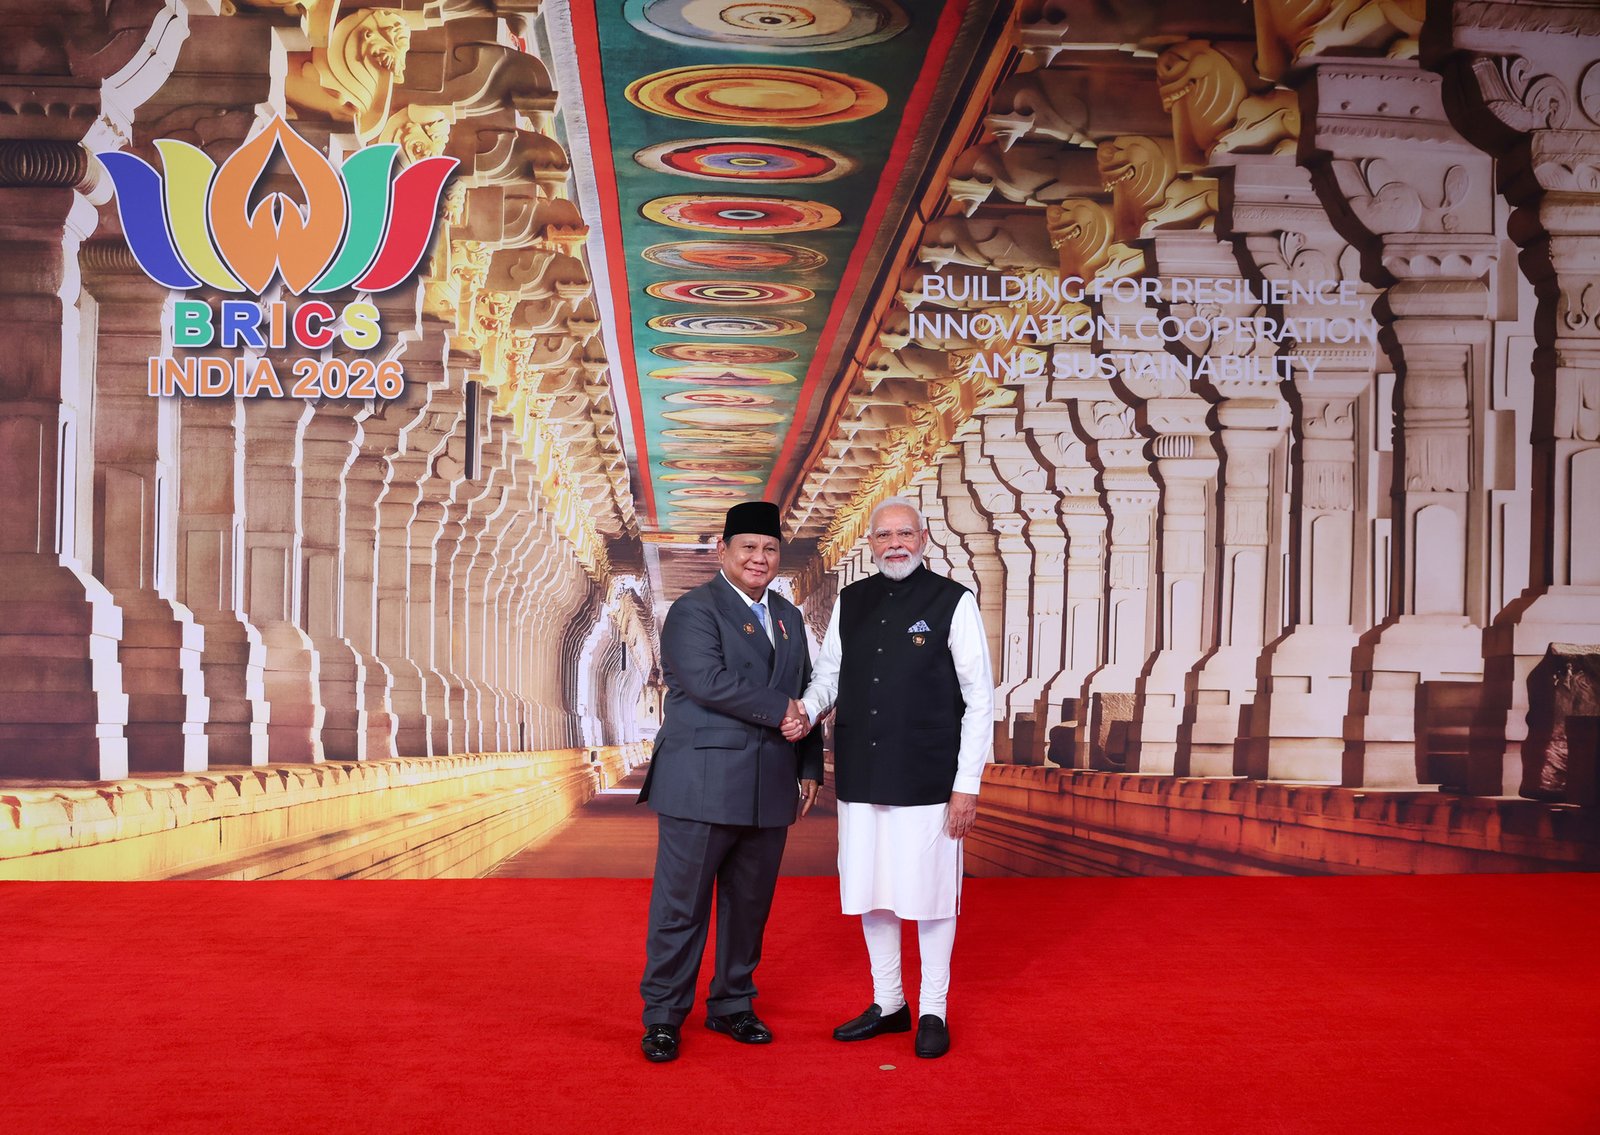
The first official issue opens at an unusual intersection. India has just hosted the 18th BRICS Summit, where leaders adopted the New Delhi Declaration and pushed cooperation on trade, finance, technology and supply-chain resilience. At the same time, disruption around Gulf energy routes is keeping Brent above $100 and testing the macro buffers India has accumulated. [S13][S14]
The summit’s economic relevance is practical rather than ceremonial. The agenda now includes more integrated BRICS markets, supply-chain stability, a proposed AI Open Source Zone, a Special Economic Zone partnership and a services-trade forum. India and China also used the summit to advance business, transport and market-access discussions while acknowledging persistent trade imbalances. [S14][S15]
But the weekend energy news is the immediate transmission risk. Saudi Arabia’s East-West pipeline – a key bypass around Hormuz – is shut after attacks. Reuters estimates that about 4 million barrels per day, roughly 4% of global supply, could be at risk if the outage lasts beyond available storage buffers. [S11]
02 | Headline Analysis – the transmission mechanism
The domestic starting point is stronger than the market mood suggests. Real GDP grew 7.8% in Q1 FY27 and July industrial production rose 6.7%. Yet July WPI inflation at 9.78% – including 20.05% for fuel and power – shows why another leg higher in energy prices matters even before it fully reaches consumer inflation. [S1][S2][S4]
The financial transmission is already visible. The rupee ended the week around 95.55 per dollar, Indian equities posted a fifth weekly loss, and the 10-year government-bond yield moved to around 7.035% as the RBI signalled active liquidity management. [S7][S8][S9]
03 | Markets & Macro Dashboard
| Indicator | Latest observation | Context | Interpretation |
|---|---|---|---|
| NIFTY 50 | 23,398.10 | -0.34% Fri; >2% lower WoW | Fifth weekly loss; oil and global-rate risk dominate. [S8] |
| BSE SENSEX | 74,781.76 | -0.16% Fri; >2% lower WoW | Large-cap risk appetite remains fragile. [S8] |
| Nifty IT | — | -5.8% WoW | Fed-rate repricing hit duration-sensitive export tech. [S8] |
| Financials | — | -1.9% WoW | Higher yields / liquidity uncertainty offset domestic growth. [S8] |
| Midcaps / Smallcaps | — | -1.4% / -0.9% Fri | Breadth deterioration was not confined to megacaps. [S8] |
| USD/INR | 95.55 | ~1% INR fall WoW | Oil import demand and risk aversion test RBI defence. [S9] |
| India 10Y G-Sec | ~7.012% | Touched ~7.035% after RBI liquidity comments | Excess liquidity and oil inflation complicate duration. [S7] |
| Brent crude | $104.61/bbl | >8% higher WoW | External shock is the dominant near-term macro variable. [S10] |
| FX reserves | $785.7bn | Record; week ended 4 Sep | Powerful spot buffer, but associated liabilities matter. [S6] |
| System liquidity | >₹10tn surplus | Post special-FX mobilization | RBI is shifting from abundance to active absorption. [S7] |
| S&P 500 | 7,656.98 | +0.86% Fri; lower on week | Fed / inflation repricing remains a global cross-asset driver. [S12] |
| Gold | ~$4,350/oz | +0.8% Fri | Safe-haven demand coexists with higher real-rate risk. [S12] |
Data discipline: cash closes, weekly moves, official macro releases, reserve stocks, liquidity estimates and global market prices are not interchangeable. Each observation keeps its original date, unit and methodology.
03 | Market Matrix – one economy, several regimes
Driver: oil + global rates + earnings-risk repricing.
Read: breadth is weak, not only index-heavyweight noise.
Driver: FX mobilization + RBI sterilization response.
Read: abundant liquidity can still coexist with rising term yields.
Driver: oil import demand vs RBI balance-sheet buffer.
Read: reserve strength reduces tail risk, not price pressure.
Driver: wholesale fuel/input pressure is ahead of household pass-through.
Read: watch the gap, not one inflation print.
04 | Global Economy & Geopolitics
BRICS New Delhi: from declaration to economic architecture
The market significance is optionality. More local-currency settlement, denser cross-border payment links, investment channels and industrial cooperation can lower frictions over time, but implementation will determine whether declarations become measurable flows. For India, the upside case is diversified financing, market access and supply-chain capacity; the risk case is that geopolitical alignment and trade imbalances limit execution.
The bilateral India-China reset matters inside that architecture. The two sides used the summit to push business and transport links, market access and a reduction of structural trade imbalances, while maintaining that border stability remains foundational. Bilateral trade reached a record $155.6 billion in 2025, with India still running a large goods deficit. [S15]
Energy geopolitics is now macro policy
BRICS called for restraint in the Middle East, but India’s near-term problem is physical: oil-market redundancy has been reduced by the Saudi pipeline outage while Hormuz risk remains elevated. Diplomacy can compress risk premia rapidly; until it changes actual supply and passage conditions, the macro channel stays live. [S11][S13]
05 | India Macro & Liquidity Radar
The RBI enters the shock with unusually strong spot foreign-exchange reserves but also an unusually large liquidity-management problem. Reserves rose $45 billion in one week to a record $785.7 billion in the week ended 4 September, largely reflecting capital inflows linked to special foreign-currency mobilization measures. [S6]
Those inflows also pushed banking-system liquidity surplus above ₹10 trillion. On 11 September, the RBI announced a ₹1 trillion open-market bond sale beginning 16 September and reiterated that bond sales and FX swaps are available to align overnight rates with the policy stance. The 10-year yield moved to around 7.035%. [S7]
06 | Rules, Policy & Release Calendar
| Regime / release | Status | Affected channels | Next watch |
|---|---|---|---|
| RBI liquidity operations | ₹1tn OMO sale announced; system surplus >₹10tn. | Banks, money markets, G-Secs, FX | 16 Sep OMO execution and overnight-rate alignment. [S7] |
| Policy repo | 5.25%; current stance unchanged at cut-off. | Loans, deposits, duration assets | Oil / inflation persistence and future MPC communication. [S16] |
| August CPI | Next major domestic inflation print due after this issue’s cut-off. | Rates, INR, consumption sectors | Whether headline inflation moves toward 5% consensus zone. [S7] |
| BRICS implementation | New Delhi Declaration adopted; workstreams move to execution. | Payments, trade, technology, investment | Concrete local-currency, payment and market-access initiatives. [S13][S14] |
07 | Research & Data Brief
Strong growth does not immunize India from an oil shock
Real GDP growth of 7.8% and July industrial production of 6.7% establish a strong domestic baseline. Gross fixed-capital formation and capital-goods output also point to investment momentum. That matters because a stronger starting point gives households, firms and fiscal authorities more room to absorb an external shock. [S1][S2]
But resilience is not the same as immunity. India remains a large net energy importer; higher crude prices first widen the import bill and demand for dollars, then work through wholesale input costs, transport and logistics, corporate margins and – depending on duration and pass-through – consumer inflation.
CPI and WPI are telling different parts of the story
July CPI inflation was 4.45% while WPI inflation was 9.78%, with fuel and power WPI at 20.05%. The gap is not a contradiction: the indices use different baskets, weights and points in the price chain. For the current thesis, WPI is the earlier warning channel and CPI is the eventual household-policy channel. [S3][S4]
08 | Company Research Lab – Reliance as an oil-beta transmission node
WHY THIS COMPANY THIS WEEK. Reliance Industries sits at the intersection of the issue’s main forces: refining and petrochemicals, domestic fuel demand, consumer activity, digital cash generation and index concentration. Its shares fell 4.9% over the week, making it a useful case study in how a diversified Indian heavyweight transmits an external energy shock rather than a recommendation. [S8]
Latest company-reported Q1 FY27 highlights show gross revenue of ₹340,257 crore, EBITDA of ₹54,067 crore, profit after tax of ₹23,196 crore and capital expenditure of ₹38,682 crore. Diversification across O2C, Jio and retail reduces reliance on a single macro driver, but it also makes simple “oil up = good/bad” narratives unreliable. [S17]
For O2C, higher crude can support some upstream economics while simultaneously raising feedstock, working-capital and demand risks; refining margins depend on product cracks, crude differentials and utilization, not crude price alone. For consumer and digital businesses, the secondary channel is household purchasing power and financing conditions.
09 | Global-to-India Transmission
India’s exposure is unusually direct because the country combines fast domestic growth with large energy imports, substantial Gulf linkages and a currency that must continuously intermediate those external flows.
July 2026 total exports of goods and services were estimated at $80.14 billion and imports at $95.16 billion. Merchandise exports were $44.24 billion and merchandise imports $76.22 billion, implying a calculated merchandise deficit of about $31.98 billion. [S5]
That starting position makes the oil shock an external-balance issue before it becomes a headline-CPI story. Higher crude and LNG acquisition costs raise dollar demand and the trade bill; a weaker rupee then amplifies landed costs. The RBI’s record reserves reduce disorderly-tail risk but do not erase the relative-price adjustment. [S6][S9]
At the corporate level, the effect is asymmetric: upstream energy can benefit, refiners depend on cracks and feedstock economics, airlines and chemicals face cost pressure, exporters gain partial currency translation, and rate-sensitive domestic sectors absorb a higher discount rate if yields rise.
10 | Signals, Risks & Scenarios
10 | Scenario Matrix – no false precision
Brent remains around $95-110, Gulf flows stay impaired but functional, the rupee remains under managed pressure, and RBI liquidity absorption keeps overnight conditions aligned without a disorderly bond sell-off.
Saudi bypass disruption lasts, Hormuz risk broadens and Brent holds well above $110. The import bill and dollar demand rise, the rupee weakens further, wholesale inflation broadens and term yields reprice higher. Equity pressure spreads from high-duration sectors to consumption and credit-sensitive cyclicals.
Saudi redundancy returns, Gulf security improves and Brent retraces below $95. The rupee stabilizes, wholesale input pressure eases and India’s strong growth / reserve buffer becomes the dominant market narrative again.
11 | Continuity & Forward Intelligence Calendar
Thesis ledger: this is official Issue #001, so there is no prior official Indian Economy & Markets Compass call to score. Baseline thesis: domestic growth is resilient; oil is the primary external shock; record reserves cushion tail risk; liquidity normalization and inflation pass-through determine whether the shock stays financial or becomes macroeconomic.
| Date | Event / status | Why it matters | What changes the thesis |
|---|---|---|---|
| 14 Sep | August India CPI release / expected | First major inflation read after July 4.45%; sets the rate narrative. | A material upside surprise strengthens oil-pass-through concern. |
| 14 Sep | Oman-led Gulf / Hormuz diplomacy watched | A credible passage / security framework can compress the oil risk premium. | Observable flow normalization, not rhetoric alone. [S11] |
| 16 Sep | RBI ₹1tn OMO sale begins | Tests the central bank’s ability to drain liquidity without disorderly term-yield repricing. [S7] | Weak absorption / sharp yield jump would tighten financial conditions faster. |
| Week ahead | Fed decision and global bond market | U.S. yields near 5% amplify the discount-rate channel into Indian equities and FX. [S12] | A less hawkish global-rate path eases the external financial shock. |
| Next 7-14d | Saudi pipeline repair / restart status | Central physical redundancy variable for global crude supply. [S11] | Restart reduces pressure; prolonged outage raises oil-tail risk. |
Calendar status is re-verified at every production cut-off. Expected dates are labelled as such and are not treated as guarantees.
12 | Alborithm Bottom Line
India is not entering this shock from a position of weakness. Q1 real GDP grew 7.8%, July IIP rose 6.7%, and FX reserves have reached a record $785.7 billion. Those are substantial buffers.
But the external price has changed faster than the domestic data. Brent is above $100, the rupee has weakened toward 95.55 per dollar, Indian equities have fallen for five consecutive weeks, and the RBI is now managing a liquidity surplus above ₹10 trillion while bond yields respond to inflation risk.
BRICS adds a medium-term strategic layer: deeper trade, payment, technology and supply-chain cooperation can widen India’s options. The immediate market test, however, is simpler. If oil normalizes before wholesale cost pressure broadens into consumer inflation and earnings, India’s growth premium survives. If not, policy will have to choose more explicitly among currency stability, liquidity, inflation and growth.
Sources, Evidence & Reader Actions
- S1 · MoSPI / PIB: Q1 FY2026-27 GDP estimates: real GDP +7.8%, 31 Aug 2026.
- S2 · PIB / MoSPI: Industrial activity factsheet: July IIP +6.7%; capital goods +16.1%.
- S3 · MoSPI / PIB: July 2026 CPI: 4.45%; food inflation 5.52%, 12 Aug 2026.
- S4 · Commerce & Industry / PIB: July 2026 WPI: 9.78%; fuel & power 20.05%, 14 Aug 2026.
- S5 · Commerce & Industry / PIB: India trade data for July 2026: exports $80.14bn, imports $95.16bn.
- S6 · RBI / Reuters: FX reserves reach record $785.7bn in week ended 4 Sep 2026.
- S7 · RBI / Reuters: Liquidity surplus above ₹10tn; ₹1tn OMO sale / liquidity-management signals, 11 Sep.
- S8 · Reuters: India stocks log fifth weekly loss; Nifty 23,398.10, Sensex 74,781.76, 11 Sep.
- S9 · Reuters: Rupee weekly pressure around 95.55/USD as oil risk rises, 11 Sep.
- S10 · Reuters: Brent settles $104.61/bbl; more than 8% weekly gain, 11 Sep.
- S11 · Reuters: Saudi East-West pipeline outage threatens about 4% of global oil supply, 13 Sep.
- S12 · Reuters: Global markets: U.S. equities, Treasury yields, gold and Fed repricing, 11 Sep.
- S13 · PMIndia: BRICS New Delhi Declaration, 18th Summit, 12-13 Sep 2026.
- S14 · Reuters: Xi pushes “Greater BRICS” economic ties, AI, SEZ and services-trade initiatives, 13 Sep.
- S15 · Reuters: India-China summit talks: business links, market access, transport and trade imbalance, 12 Sep.
- S16 · RBI: Current policy-rate framework / repo 5.25% at issue cut-off.
- S17 · Reliance Industries: Q1 FY2026-27 financial and operational performance, 17 Jul 2026.
- S18 · PIB / PMO: 18th BRICS Summit official event record and approved summit image source.
- S19 · Alborithm Research: Calculated merchandise deficit: $76.22bn imports – $44.24bn exports = $31.98bn.
- S20 · Alborithm Research: Market/macro transmission framework; scenario and linchpin analysis.
- S21 · User-approved master: Exact Alborithm logo and BRICS event image reused from supplied reference artwork.
- S22 · Document control: Issue #001 / Week 37; data frozen at 13 Sep 2026, 21:50 IST.
Document Control & Reader Actions
Indian Economy & Markets Compass — PDF Edition
Download the complete 12-page edition covering BRICS 2026, $100+ oil, the Indian rupee, RBI liquidity, inflation, GDP, markets, scenarios and the week ahead.
Subscribe to alborithm
Get new documentaries, articles and podcasts directly in your inbox.